Ndax Wealth: Market Report Oct 20
Every other week, we break down the cross-asset landscape, from crypto to equities to commodities, so you can stay ahead of the macro trends shaping global markets. Here’s your snapshot of what mattered, why it moved, and what to watch next.
Desk View
Crypto
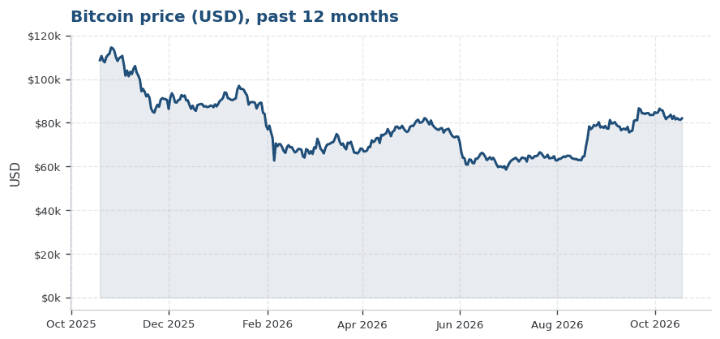
Pressure and rebound: Bitcoin enters the week near $82,000 USD after hotter U.S. inflation and pressure on technology equities pushed the price toward $80,000 USD and triggered leveraged liquidations. U.S. spot Bitcoin ETFs recorded approximately $228 million USD in net outflows last week, following roughly $681 million USD the week prior.
Ownership trends paint a more nuanced picture. Glassnode estimates the average cost basis of U.S. spot Bitcoin ETF holdings near $81,500 USD. CryptoQuant data shows wallets holding at least 1,000 BTC added approximately 70,000 BTC in aggregate between late September and early October, a contrast between ETF redemptions and large on-chain accumulation.
Beneath the surface: Altcoins corrected more sharply, with Ethereum, Solana and XRP underperforming Bitcoin, and Cardano, NEAR Protocol (NEAR) and Avalanche (AVAX) among the week's weaker performers. CoinGlass's Altcoin Season Index retreated to 50 after approaching the low 70s earlier in October, while the Crypto Fear and Greed Index moved back toward neutral territory. Bitcoin's behaviour around $80,000-$81,500 USD and renewed ETF activity will provide useful context ahead of the October 27-28 Federal Reserve meeting.
Macro
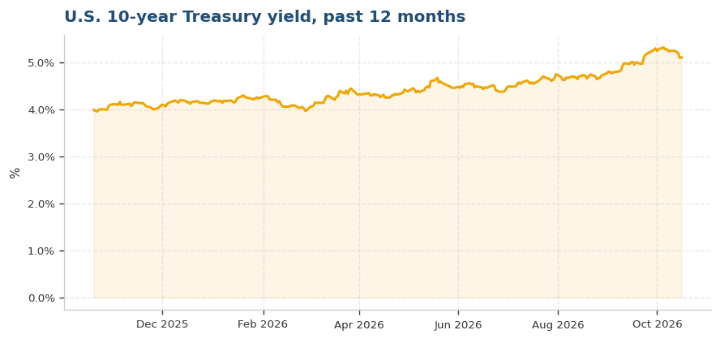
Hotter inflation: September U.S. CPI rose 3.7% year-over-year, exceeding the 3.6% consensus and accelerating from August's 3.4%. Higher gasoline prices contributed, and core inflation also beat expectations. The report arrived against a softer employment backdrop, with September payroll growth of 29,000 and downward revisions to earlier months. Markets initially increased expectations for further tightening, though subsequent remarks from Federal Reserve Chair Kevin Warsh were read as leaving room for a pause at the October meeting.
Abroad and ahead: China's third-quarter GDP expanded 4.5% year-over-year, while political and fiscal uncertainty in France continued to attract attention in European markets. This week's U.S. calendar is comparatively light. The bigger events arrive the following week, when the Federal Reserve's October 27-28 policy meeting will coincide with additional growth and inflation data. U.S.-Iran negotiations also remain relevant for energy prices.
Equities
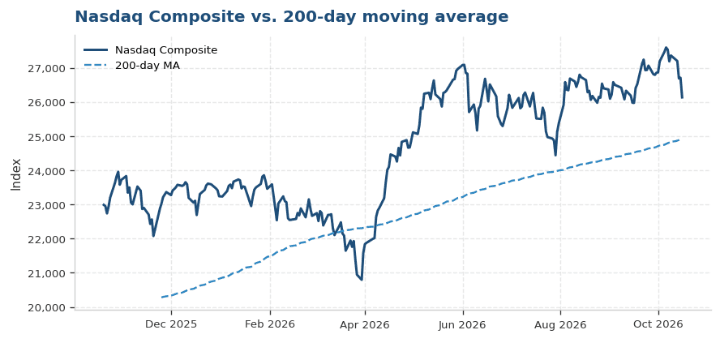
A tech-led split: U.S. equities diverged sharply last week as concerns over AI infrastructure spending and elevated financing costs weighed on technology shares. The Nasdaq declined approximately 4.5%, the S&P 500 fell around 2%, and the Dow Jones Industrial Average gained roughly 0.7%. The Philadelphia Semiconductor Index declined approximately 11%, with CoreWeave attracting scrutiny as investors reassessed debt requirements for large-scale data-centre investment. The weakness reflects growing attention to AI financing economics, rather than a change in long-term adoption expectations.
Third-quarter earnings now offer an opportunity to assess those concerns. Meta Platforms and Tesla report Wednesday, alongside Netflix, GE Aerospace, General Motors, IBM and Lam Research. Meta's commentary on how AI-related capital expenditure is translating into advertising performance will be particularly relevant, while semiconductor and infrastructure results should provide insight into demand and margins. The question for equities is increasingly one of earnings quality and capital efficiency, rather than revenue growth alone.
Fixed Income, FX & Commodities
Headlines Worth Noting
OTC Desk, Let's Talk
Don't forget to follow us on social media for more updates and join the conversation on our forums.
Disclaimer: This article is not intended to provide investment, legal, accounting, tax or any other advice and should not be relied on in that or any other regard. The information contained herein is for information purposes only and is not to be construed as an offer or solicitation for the sale or purchase of cryptocurrencies or otherwise.